Every profitable NHL bettor I know has one thing in common: they never ask “who will win?” before asking “what is the fair price?” That distinction is the entire game. A team can be likely to win and still be a bad bet if the odds do not compensate for the risk. A team can be likely to lose and still be a brilliant bet if the odds overcompensate. Value betting is the discipline of pricing outcomes independently of the bookmaker and then acting only when the gap between your price and theirs is wide enough to overcome the house margin.
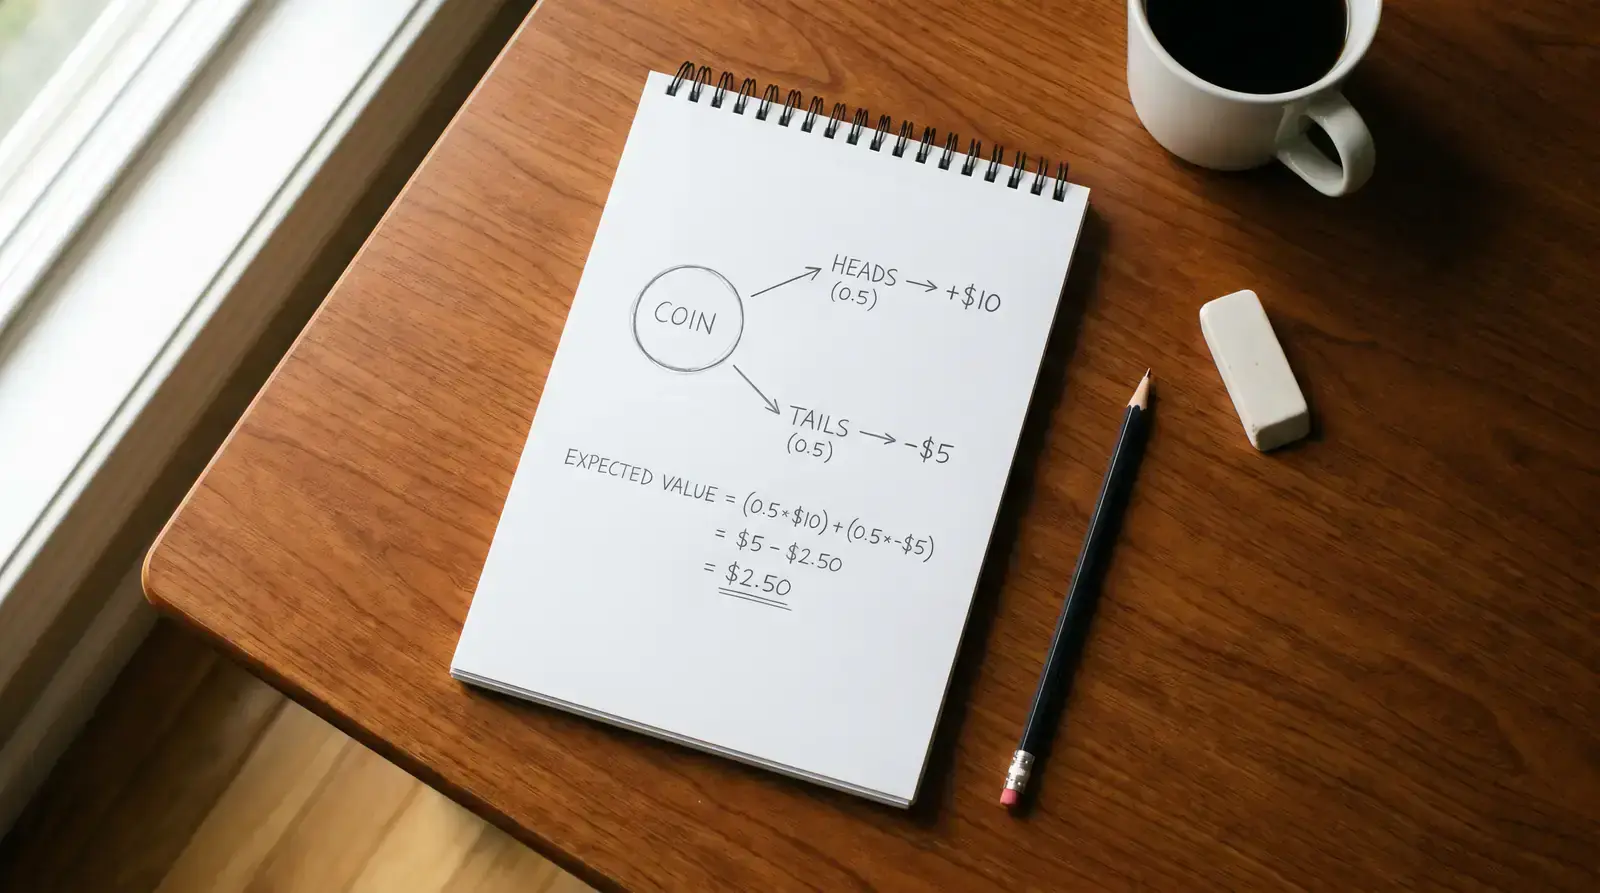
NHL underdogs won 39.1% of all games in the 2024-25 season. That number is useless in isolation. It becomes powerful when you compare it to the implied probability embedded in the odds. If an underdog is priced at 3.00, the bookmaker implies a 33.3% chance of winning. If your analysis says the true probability is 40%, you have a 6.7 percentage-point edge — a value bet that will produce profit over a large enough sample regardless of whether it wins tonight.
What Is Value
Value exists when the true probability of an outcome exceeds the implied probability of the offered odds. The concept is simple; the execution is not. The difficulty lies in estimating the “true probability” accurately enough to identify genuine mispricing rather than seeing edges where none exist.
Home underdogs in the NHL won 44.4% of games outright in 2024-25. The average decimal odds on those home underdogs implied a win probability closer to 35-38%. That 6-9 percentage-point gap is not a one-season anomaly — it has persisted across multiple years, which is why the home underdog segment is one of the most reliable sources of structural value in hockey betting. The market consistently underestimates the combination of home-ice advantage, last-change rights, and the goaltending lottery that gives underdogs a better shot than their price suggests.
But value is not limited to underdogs. It exists anywhere the bookmaker’s model disagrees with reality. A favourite priced at 1.55 who should be 1.45 is also a value bet — the edge is just smaller and harder to identify because the market is more efficient on the favourite side. I find more value on underdogs and totals than on favourites simply because those markets attract less sharp money and retain more inefficiency.
Implied vs True Probability
The mechanical process of value betting starts with converting odds to implied probability. Decimal odds of 2.50 imply 40%. Odds of 1.80 imply 55.6%. Odds of 3.20 imply 31.3%. These conversions should be automatic — if they are not, drill them until they are, because every value assessment begins with this step.
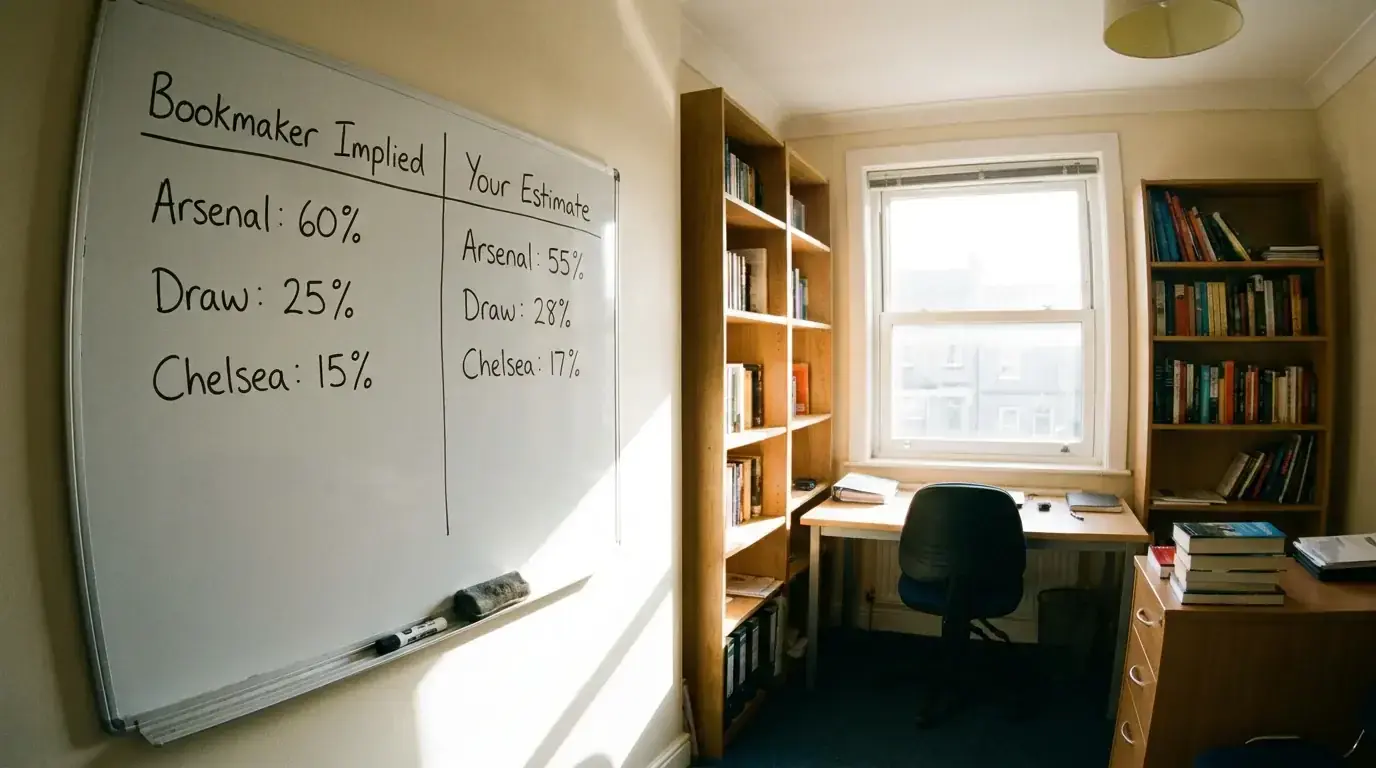
The most common total in the NHL is 6.5 goals. An over priced at 1.91 implies 52.4%. If your model says the over probability for a specific game is 57%, you have a 4.6-point edge. At that edge, betting the over at 1.91 produces positive expected value of roughly 9 pence per pound wagered. Over a season of 200 totals bets at 10 pounds each, that is 180 pounds of expected profit — real money that accumulates invisibly, bet by bet, regardless of individual outcomes.
Estimating the true probability is where skill separates profitable bettors from break-even ones. I build my estimates from four inputs: team-level expected goals (both for and against), goaltender save percentage in the current form window, schedule-spot adjustments (rest, travel, back-to-back), and home-ice modifier. Each input contributes a probability estimate, and I average them with weighting that favours goaltending and expected goals over schedule and home-ice. The resulting number is my true probability, and I only bet when it exceeds the implied probability by 4 percentage points or more on the moneyline, or 3 percentage points on totals.
The Screening Process
I do not analyse every game on the board. Screening filters eliminate roughly two-thirds of the daily card before I open a single data source, which preserves my analytical energy for the games most likely to contain value.
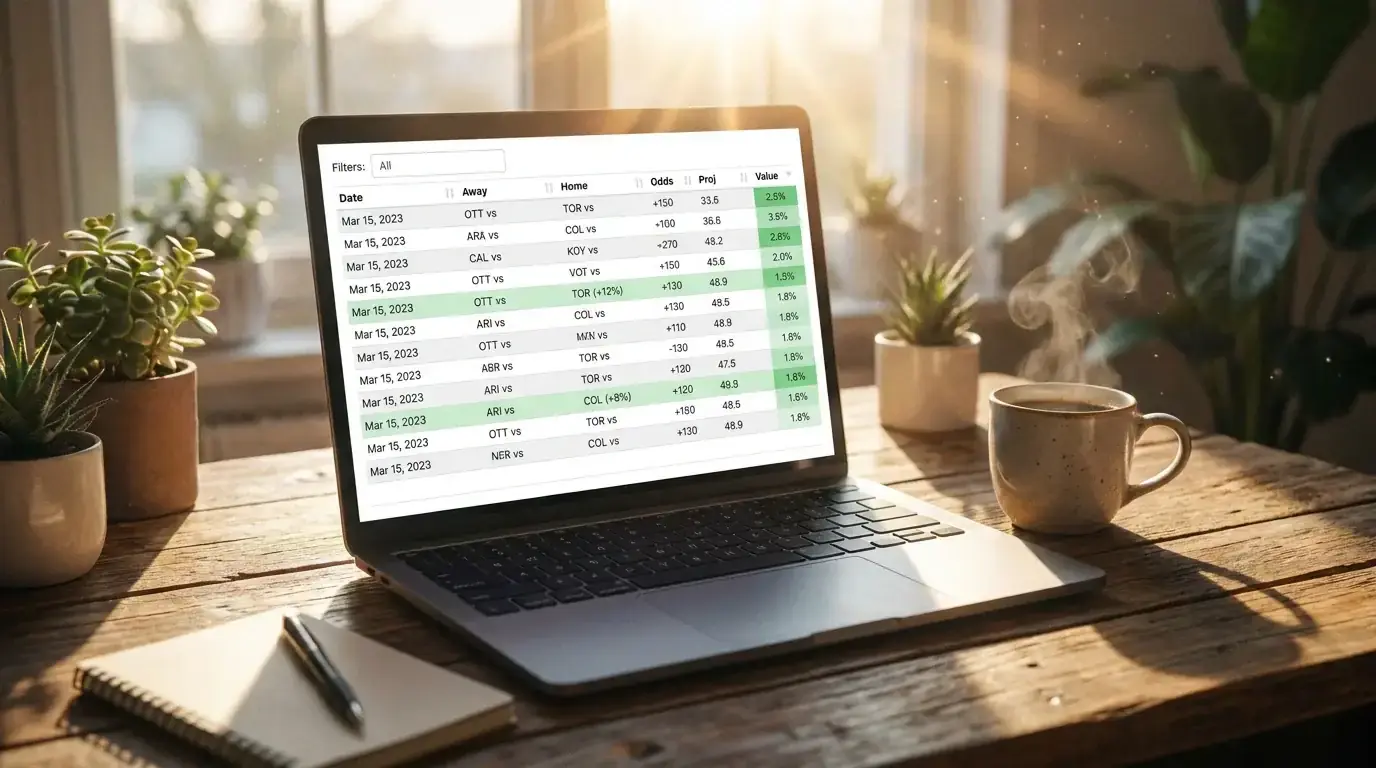
Filter one: home-ice check. Home teams won 56.6% of games in 2024-25. If the home team is a slight underdog or a short favourite, the game passes to filter two. Heavy favourites and heavy underdogs are priced more efficiently and rarely contain enough value to justify the analysis time.
Filter two: goaltender confirmation. If both starters are confirmed and I can locate their rolling five-game save percentages, the game passes to filter three. If one or both goaltenders are unconfirmed, I hold the game in a pending queue and revisit after announcements.
Filter three: schedule-spot flag. I check whether either team is on the back end of a back-to-back, on a long road trip, or in a rest-day mismatch. Games with a meaningful schedule-spot differential pass to the full analysis. Games with no schedule edge go to the bottom of my priority list.
After screening, I typically have four to eight games that warrant full analysis. Of those, two or three will produce a value signal strong enough to bet. That selectivity is the hardest part of the process — the temptation to bet more games is constant, and the discipline to bet fewer is what separates the bettors who compound an edge from the bettors who drown it in volume.
Turning Process into Profit
The value betting process I have described sounds mechanical, and it is. That is its strength. Mechanical processes produce consistent results because they remove the emotional noise that causes most bettors to deviate from their edge. I do not have “gut feelings” about NHL games. I have a screening filter, a probability estimate, and a comparison to the offered odds. When the gap exceeds my threshold, I bet. When it does not, I pass — even if the game looks interesting, even if my favourite team is playing, even if social media is buzzing about a “lock.”
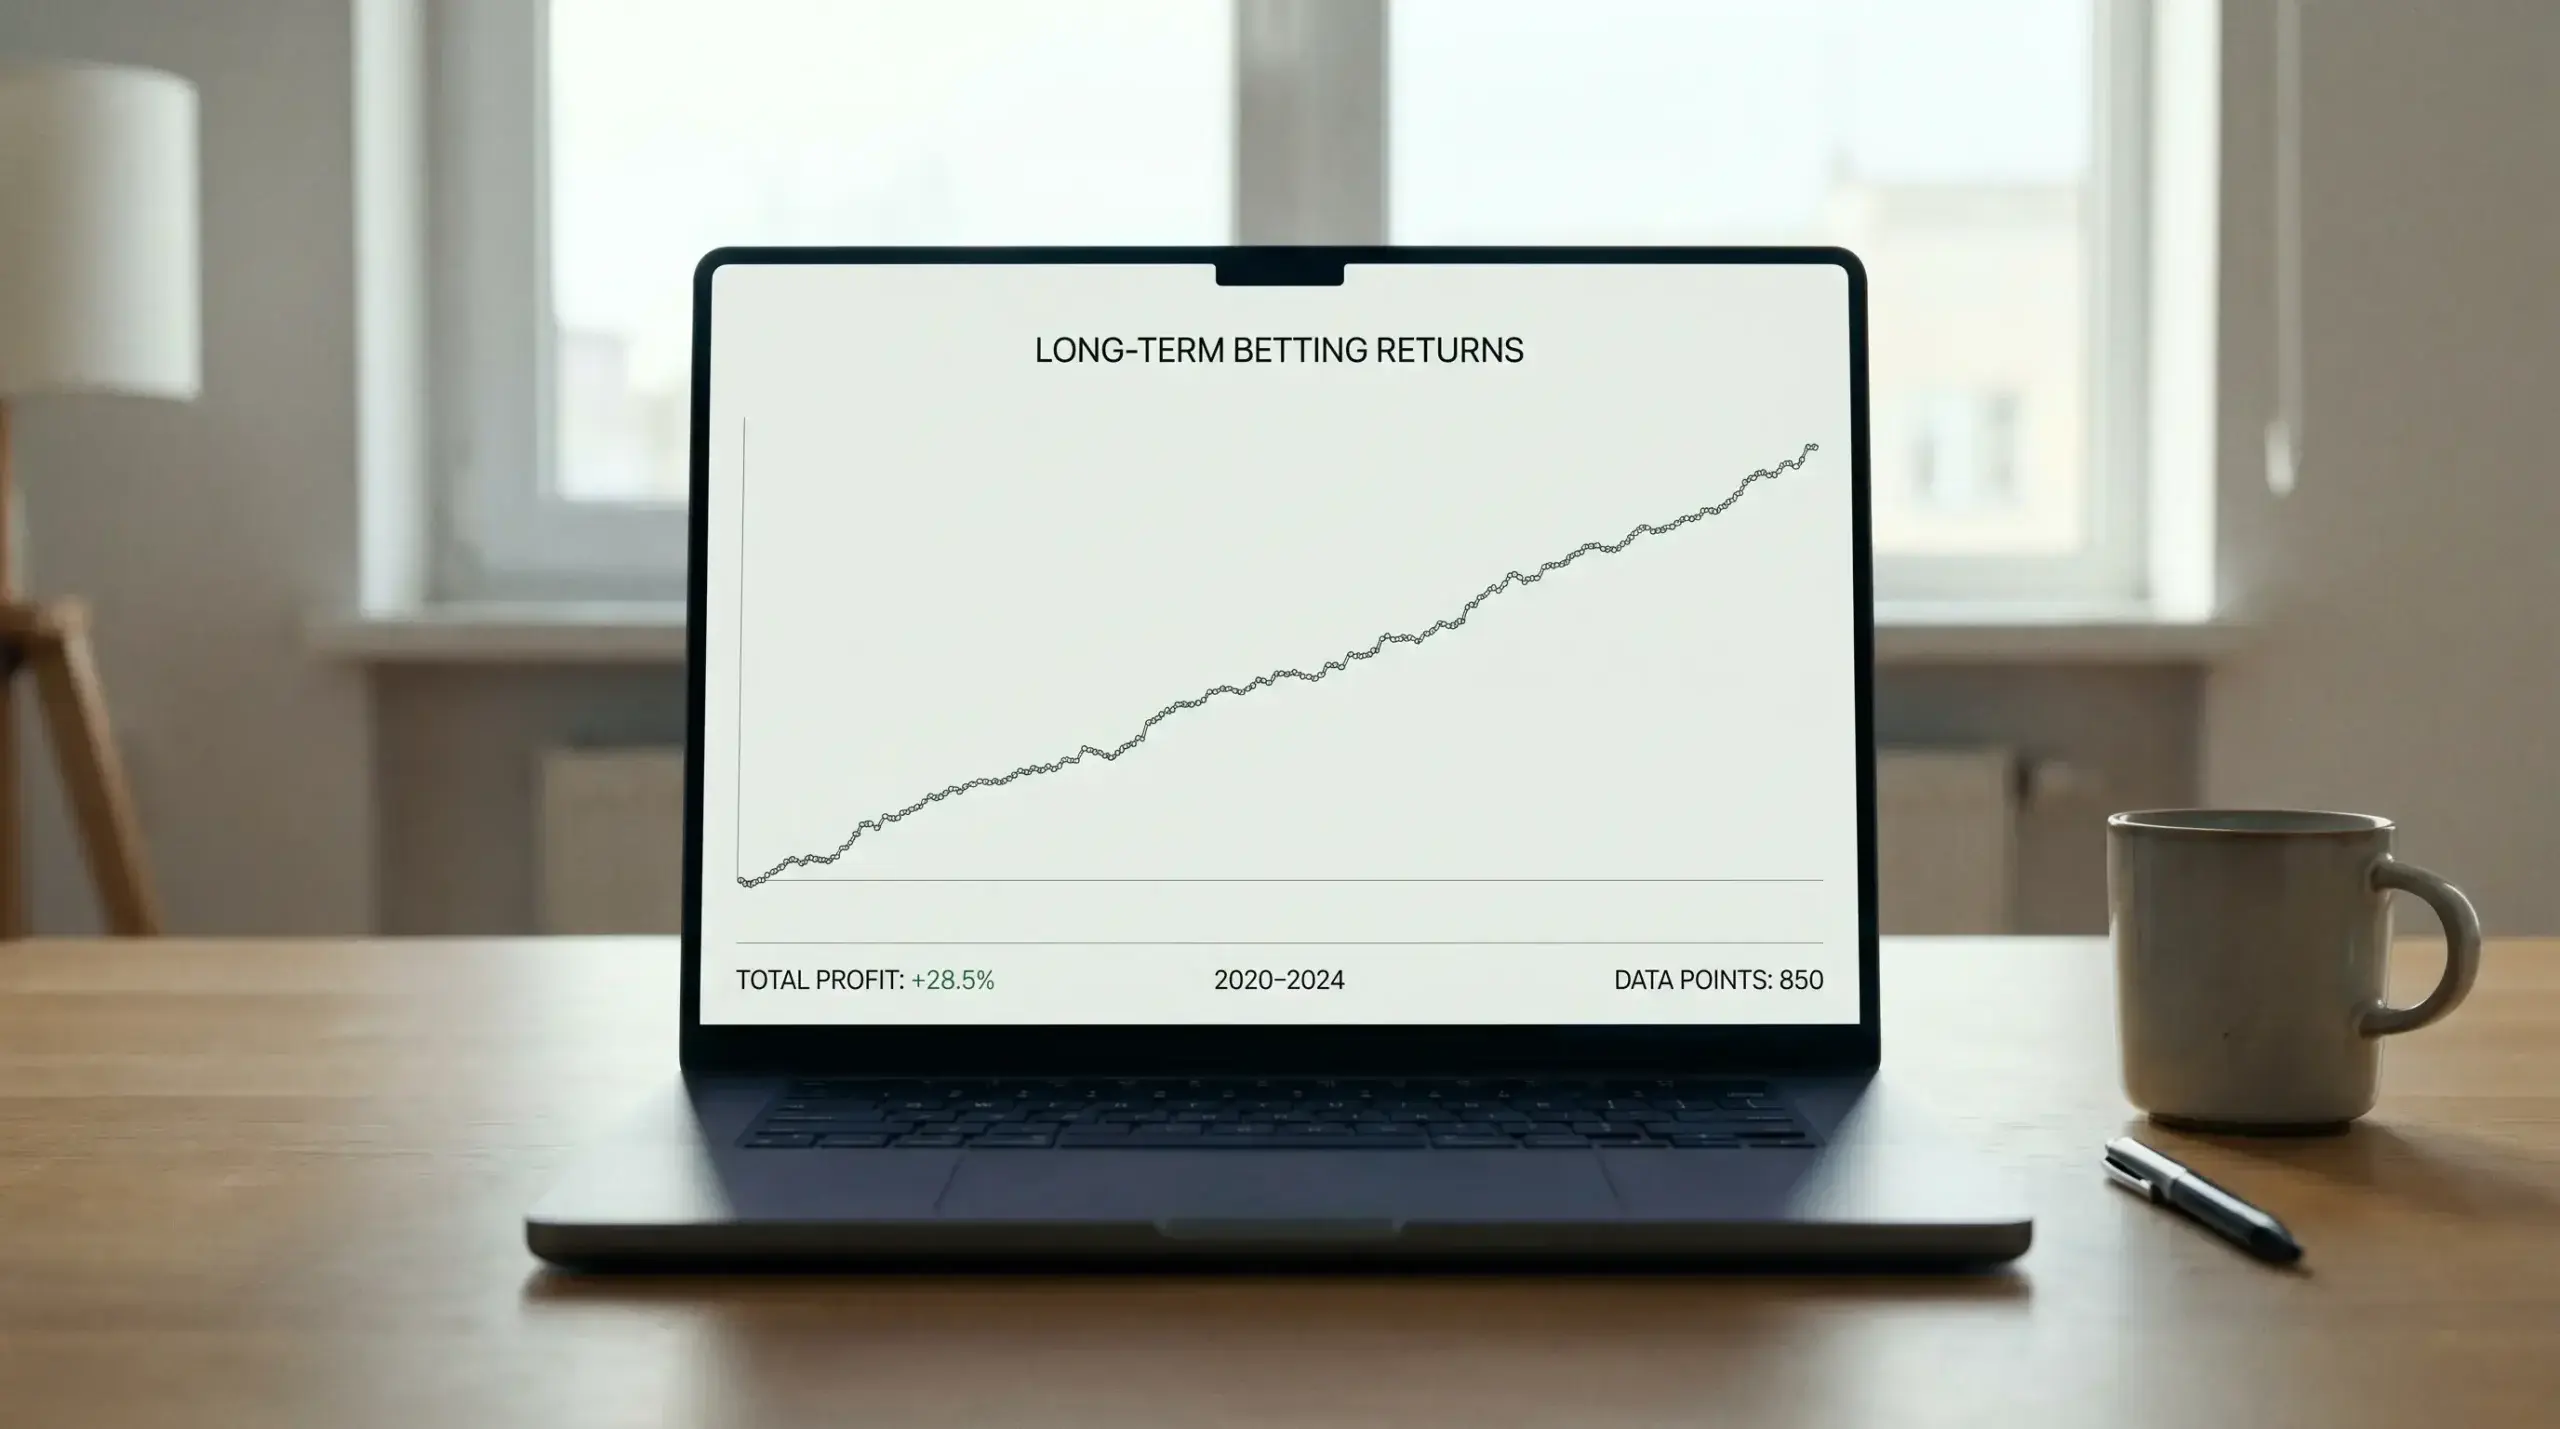
The results take time to materialise. Value betting is a large-sample enterprise. Over 50 bets, variance dominates and you might be negative despite having a genuine edge. Over 200 bets, the edge begins to assert itself. Over 500 bets, the results converge on your true expected value with enough precision to evaluate the system’s strength. I commit to a minimum of one full NHL season before judging whether my process is working — anything less is evaluating noise rather than signal. The bettors who expect immediate gratification from value betting are the ones who abandon it after a bad month, and the bettors who treat it as a patient, data-driven enterprise are the ones still profitable five seasons later.